


CASCO can be arranged for both a new and a used car, but the insurance terms may differ significantly. They are influenced by the year of manufacture, market value, technical condition, existing damage, repair conditions, selected risks and deductible. For a new car, the insured amount is usually based on the purchase price, while for a used car it is based on the current market value, taking age and wear into account. Before taking out a policy, it is important to compare not only the price, but also the repair conditions, exclusions and the way the vehicle is assessed.
CASCO protects your own vehicle against damage, theft, fire, natural disasters and other risks specified in the contract. Unlike RCA, which covers liability towards third parties, CASCO is designed specifically to cover damage to your own car.
At the same time, the same make and model may be offered different insurance terms depending on whether the vehicle is new or used. The reason is not only the age of the car: the insurer also assesses its actual value, condition, potential repair costs and other risk factors.
Below, we explain how CASCO for a new car differs from insurance for a used vehicle and what is especially important to check before signing the contract.
Why CASCO terms depend on the vehicle
CASCO is voluntary insurance, so its terms are determined by the insurer within the contract and its internal risk assessment rules.
The calculation and structure of the policy may be influenced by:
- year of manufacture;
- make and model;
- current market value;
- technical condition;
- usage history;
- existing damage;
- repair conditions;
- territory of coverage;
- number of drivers;
- selected risks;
- deductible amount.
For new cars, the purchase price usually serves as the starting point when determining the insured amount. For used vehicles, the actual market value and age are taken into account. In CASCO insurance practice, the insured amount for a used car may also be determined using the depreciation scale applied by the insurer.
That is why it is not enough to compare two policies only by the insurance premium. A more important question is what you will actually receive in the event of an insured loss and under what conditions the vehicle will be repaired.
CASCO for a new car
A new car usually has a high value and has not yet accumulated damage from normal use. For the owner, it is therefore especially important to preserve its value and ensure access to high-quality repairs.
For a new car, it is worth checking:
- at what value the car is accepted for insurance;
- where repairs will be carried out;
- whether repairs at an authorised dealer are allowed;
- what parts are provided for under the policy terms;
- whether there are restrictions for specific components;
- whether theft is covered;
- whether natural disasters, fire and unlawful actions of third parties are included;
- whether a replacement car is provided during repairs.
On Superpolis, CASCO FULL and PREMIUM options are available, as well as CASCO with a deductible. PREMIUM may include a replacement vehicle during the repair period, which is especially useful when a new car is used every day.
For a vehicle purchased on credit or lease, the requirements of the bank or leasing company must also be taken into account. In such cases, CASCO may be a mandatory financing condition, and the lender may set requirements regarding the insurer, covered risks, deductible and policy term.
CASCO for a used car
A used car can also be insured under CASCO. However, the insurer will assess it based on its current value and condition.
The insured amount is usually determined according to the vehicle’s actual market value at the time the policy is issued. For a used car, age and wear may also be taken into account.
Before insuring a used vehicle, it is important to clarify:
- whether a vehicle of this age is accepted for insurance;
- how its insured value is determined;
- what damage has already been recorded before the start of the contract;
- what repair conditions apply;
- how depreciation is taken into account;
- whether there are restrictions on parts and components;
- whether full coverage is available or another type of programme is offered;
- what deductible options are available.
The older the vehicle, the more important it is to read the policy terms carefully. Different insurance companies may have different approaches to vehicle age, repairs and the valuation of parts.
That is why it is especially useful to compare several offers for a used car rather than accept the first available option.
How age and mileage affect the terms
The age of the vehicle primarily affects its market value and the insurer’s risk assessment.
A new car has a clear purchase price. For a used car, the value already depends on age, condition, equipment, the market and other factors.
Insurers may take the age of the car into account when determining:
- the insured amount;
- the tariff;
- available coverage options;
- repair conditions;
- the applicable deductible;
- rules for valuing parts;
- whether the vehicle can be accepted for insurance at all.
Mileage can also indicate the degree of vehicle use, but the specific importance of this factor depends on the rules of the particular insurance company.
If you are interested specifically in the cost of CASCO and the factors that influence it, you can also read the article “How much does CASCO cost in Moldova: what affects the price and how to get an accurate quote”.
Why the insurance company requests a vehicle inspection
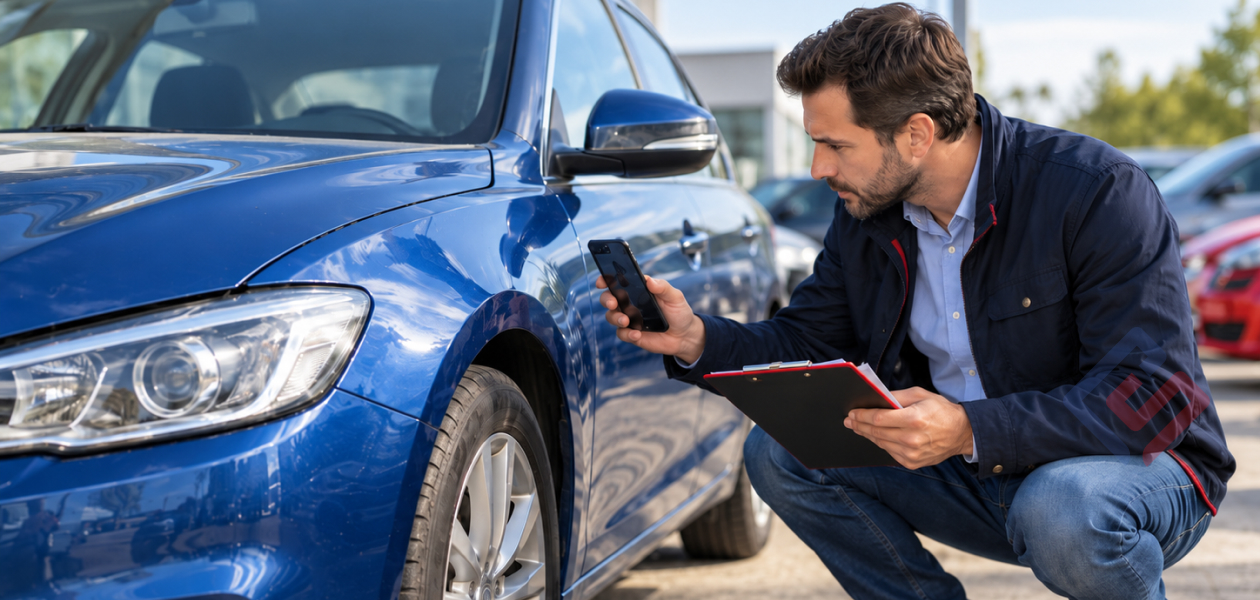
Before concluding a CASCO contract, the insurer carries out an inspection and takes photographs of the vehicle.
This is especially important for used cars because it is necessary to determine which damage already existed before the insurance coverage began.
During the inspection, the following may be recorded:
- body condition;
- scratches and dents;
- condition of the windows;
- headlights;
- wheels;
- interior;
- additional equipment;
- other visible damage.
This is also important for the owner: damage recorded before the contract is concluded is generally not treated as a new insured event.
Which risks are especially important for a new car
For a new car, FULL CASCO is particularly suitable because even minor damage — scratches, dents or other body defects — often needs to be repaired at an authorised dealer if the vehicle was purchased new from a showroom in Moldova and is still under warranty.
Repairs at an authorised dealer are usually more expensive, while servicing the car at a non-authorised repair shop may, in certain situations, affect the warranty conditions. Broad coverage therefore helps reduce the risk of significant expenses even in the case of relatively minor damage.
It is worth paying attention to coverage for:
- road accidents, including situations where the insured driver is at fault;
- theft;
- fire and self-ignition;
- hail and other natural events;
- falling branches and other objects;
- unlawful actions of third parties;
- damage to specific parts and equipment;
- towing after an insured event.
For a new vehicle, it is also particularly important to clarify the repair conditions. Two policies with a similar list of risks may differ significantly depending on where and how the vehicle will be repaired.
Which risks are important for a used car
For a used vehicle, the priorities may be slightly different.
Owners are often especially interested in protection against major expenses caused by:
- a serious road accident;
- theft;
- fire;
- hail, flooding and other natural events;
- vandalism;
- falling trees or other objects;
- significant body damage.
At the same time, the owner may be willing to pay for minor scratches or insignificant damage themselves. In this case, a policy with a deductible may be more practical than coverage without any financial participation by the policyholder.
However, the age of the car does not automatically mean that it only needs minimal protection. A used vehicle may still have a high market value, be the family’s main means of transport or be used every day. In this case, broad CASCO coverage remains fully justified.
How the deductible helps adjust CASCO terms
The deductible is the part of the loss that the policyholder pays themselves in the event of an insured claim.
It may be set as a fixed amount or as a percentage — the specific mechanism depends on the contract.
A simple example: if the policy includes a deductible, minor damage may remain entirely at the owner’s expense, while in the event of a larger loss the insurance company will pay compensation after deducting the agreed deductible.
For a new car, the owner may prefer a minimal deductible if they want the broadest possible protection even for smaller damages.
For a used car, a higher deductible can sometimes be a way to retain protection against major losses without paying extra for every minor repair.
However, the deductible should not be chosen solely to reduce the policy price. It is important to understand in advance how much you are prepared to pay out of pocket after an accident or another insured event.
What documents will be required
To arrange CASCO through Superpolis, you will need:
- the vehicle registration certificate;
- the owner’s personal details;
- driving licences of the persons authorised to drive the vehicle.
For the quote, information about the vehicle will also be required:
- make;
- model;
- year of manufacture;
- value;
- selected CASCO option;
- preferred deductible.
If the vehicle is financed through a loan or lease, additional information about the financing and the requirements of the bank or leasing company may also be required.
What to compare besides price
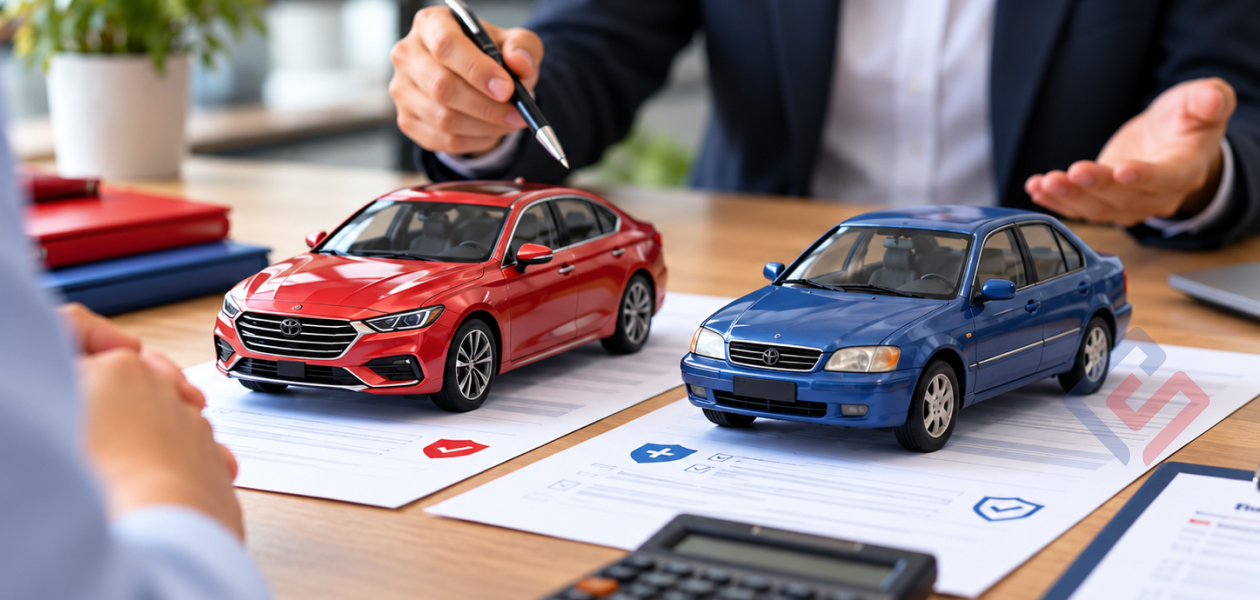
When choosing CASCO for a new or used vehicle, it is useful to compare several parameters at the same time:
- insured amount;
- list of covered risks;
- deductible;
- repair conditions;
- exclusions;
- territory of coverage;
- requirements for drivers;
- procedure for notifying the insurer of an insured event;
- additional services;
- rules regarding pre-existing damage.
On Superpolis, you can request a CASCO quote. The broker helps compare both the price and the contract terms.
FAQ
Is there a maximum vehicle age for CASCO?
There is no single universal limit that applies to all insurers. Age restrictions and available coverage options are determined by each insurance company.
Do I need to show the vehicle to the insurer before taking out the policy?
Yes. The insurer requires an inspection and photographs of the vehicle in order to record its condition and any existing damage before the contract begins. This is especially relevant for used vehicles.
How does the insured amount differ for a new and a used car?
For a new car, the purchase price is usually the main reference point. For a used car, the current actual or market value is used, taking into account age and the insurer’s approach to depreciation.
Can the deductible be changed?
Insurers usually offer several deductible options. The more risk the driver is prepared to retain, the more this may affect the terms and cost of the policy.
Request a CASCO quote for your vehicle
Both new and used cars can be insured under CASCO, but they should not be assessed according to the same criteria. For a new car, the purchase price, high-quality repair conditions and protection of its high value are especially important. For a used car, the current market value, condition, recorded damage and repair specifics matter more.
Before taking out a policy, check:
- how the insured amount is determined;
- which risks are included;
- whether a preliminary inspection is required;
- where and how the vehicle will be repaired;
- what deductible applies;
- which types of damage are excluded;
- whether there are age restrictions;
- which additional services are included in the policy.
This will help you choose CASCO not simply by price, but by how well the contract actually suits the specific vehicle.
→ Request a CASCO quote on Superpolis.md